

 125 / 364

4.1 CONSOLIDATED FINANCIAL STATEMENTS AND NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
Note 11. Other financial investments, other financial income (expense)
DANONE
REGISTRATION DOCUMENT 2015
125
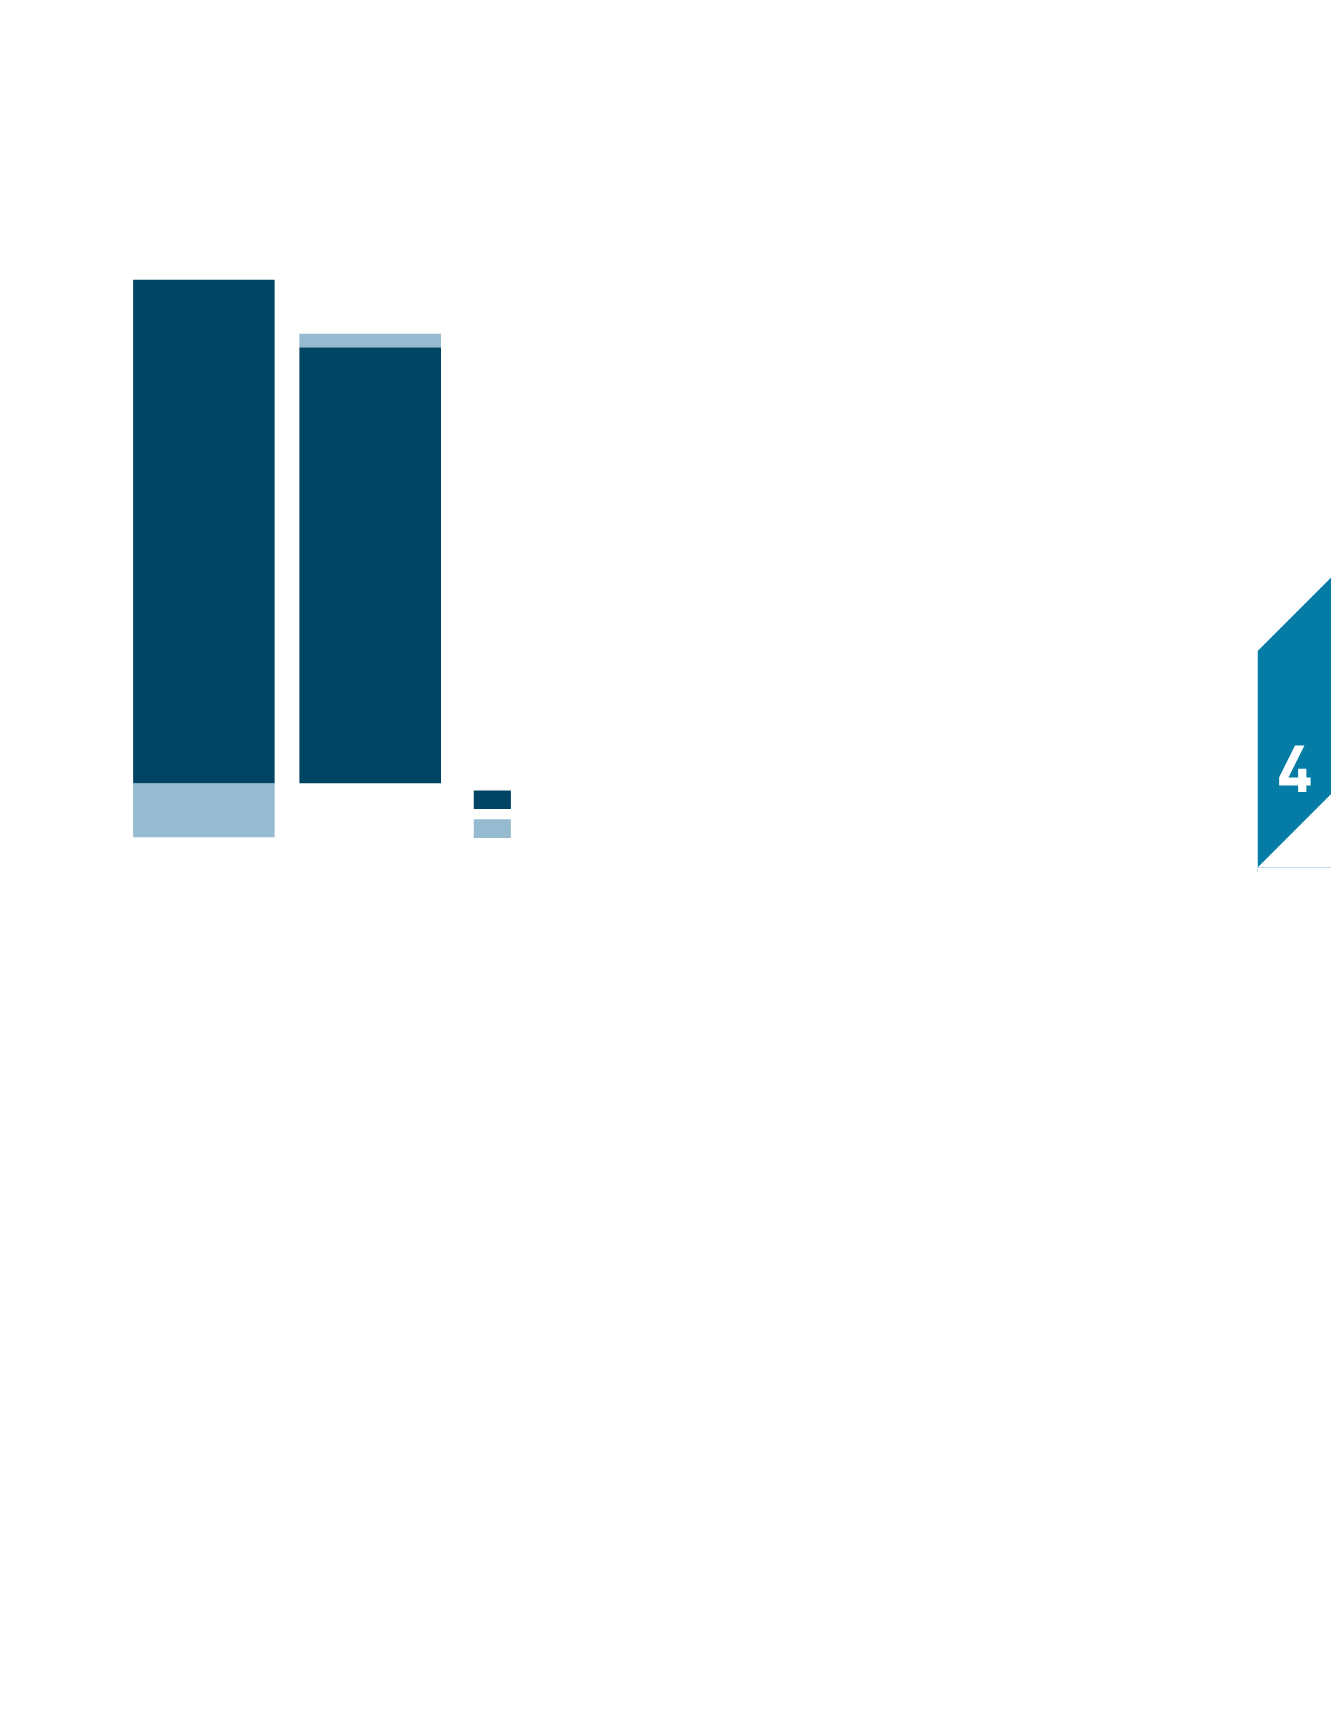
Hedged and unhedged portion of net debt in respect
of an increase in short-term interest rates
Fixed and floating rate net debt breakdown
2014
2015
-12%
112%
97%
3%
Sensitivity of the cost of net debt to a change in the short-term
interest rate
In 2015 as in 2014, the impact of a change in short-term interest
rates would not have a significant impact on the cost of the Group's
net debt.
Financial currency risk
Due to its international presence, the Group could be exposed
to foreign exchange rate fluctuations in relation to its financing
activities: in application of its risk centralization policy, the Group
manages multi-currency financings and liquidities.
In application of its financial currency risk hedging policy, the Group's
residual exposure (after hedging) is not material.
As part of these policies, the Group uses cross-currency swaps as
described in Note 12.4 of the Notes to the consolidated financial
statements.
NOTE 11. OTHER FINANCIAL INVESTMENTS, OTHER FINANCIAL INCOME
(EXPENSE)
Note 11.1. Accounting principles
Investments in other non-consolidated companies
Investments in other non-consolidated companies are measured as
available-for-sale investments within themeaning of IAS 39,
Financial
Instruments: Recognition and Measurement
. They are recognized at
fair value in the consolidated balance sheet, with changes in fair
value recognized under consolidated equity in Accumulated other
comprehensive income, except for unrealized losses that are consi-
dered to be significant or prolonged, which are recognized directly
in profit or loss in Other financial income (expense).
Fair value
For listed companies, fair value is assessed according to the stock
price as of the end of the period.
For unlisted companies, fair value is assessed based on recent
transactions entered into with third parties, put or call options
negotiated with third parties or external appraisals.
When such elements do not exist, the fair value of investments in
unlisted companies is deemed to be equivalent to the acquisition
cost of the investments.
Gains or losses on disposal of non-consolidated investments are
recognized under the heading Other financial income (expense) in
the consolidated income statement.
Other long-term financial assets
Other long-term financial assetsmainly comprise bonds andmoney-
market funds and security deposits required by the tax regulations
of certain countries in which the Group operates.
Bonds and money-market funds are classified as available-for-sale
financial assets within the meaning of IAS 39,
Financial Instruments:
Recognition and Measurement
. They are recognized at fair value in the
consolidated balance sheet, with changes in fair value recognized
under consolidated equity in Accumulated other comprehensive
income, except for unrealized losses that are considered to be
significant or prolonged, which are recognized directly in profit or
loss in Other financial income (expense). Their fair value is calculated
on the basis of listed prices on active markets.
Long-term loans
Long-term loans are measured at amortized cost using the effec-
tive interest rate method within the meaning of IAS 39,
Financial
Instruments: Recognition and Measurement
.
Fixed rate
Floating rate