

 210 / 302

Consolidated Financial Statements as of December 31, 2015
Notes to the Consolidated Financial Statements
Finance costs and other financial income and expenses
12.5
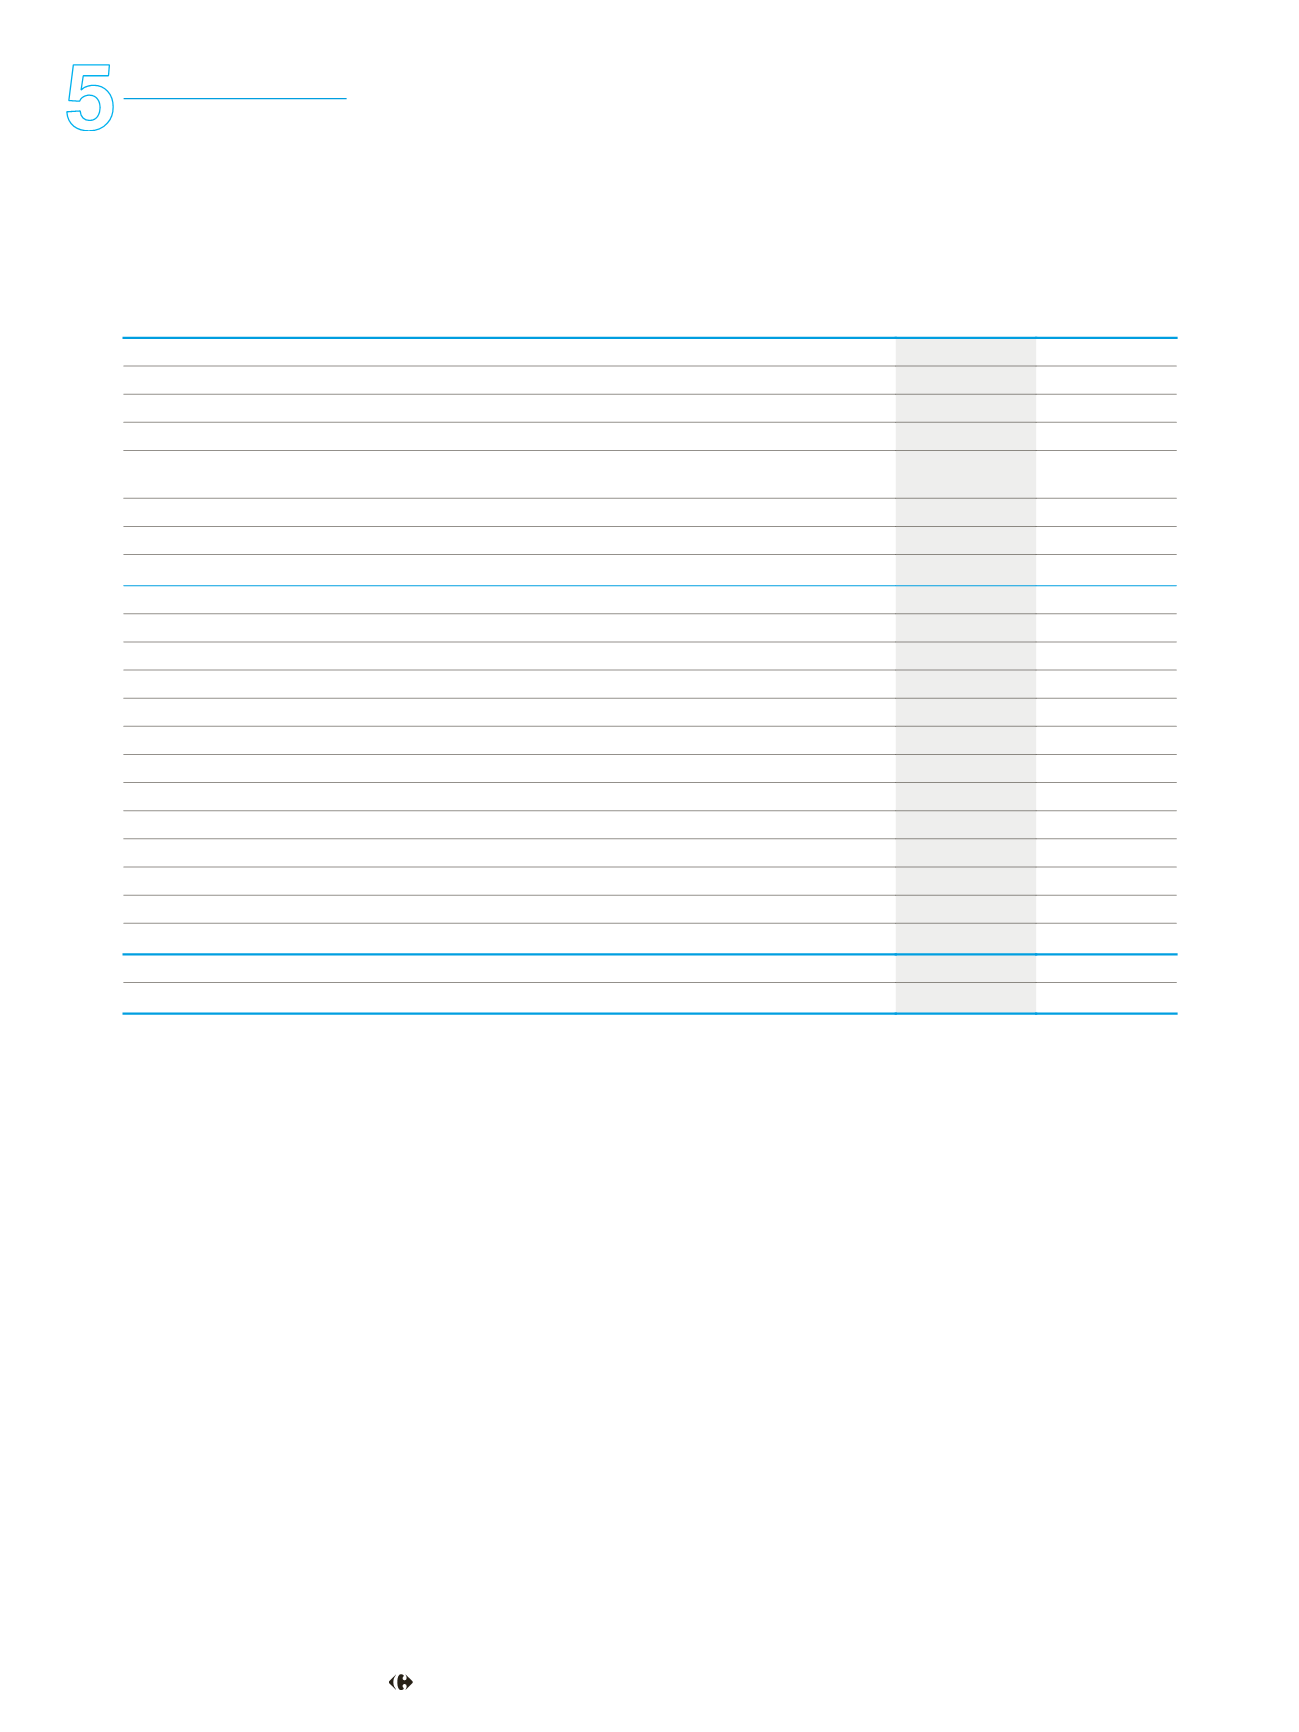
This item breaks down as follows:
2015
2014
(in millions of euros)
Interest income from loans and cash equivalents
32
35
Interest income from bank deposits
30
31
Interest income from loans
2
4
Finance costs
(380)
(434)
Interest expense on financial liabilities measured at amortized cost, adjusted for income and
expenses from interest rate instruments
(352)
(406)
Interest expense on finance lease liabilities
(27)
(28)
Ineffective portion of fair value hedges of borrowings
-
(0)
Finance costs, net
(347)
(399)
Other financial income and expenses, net
(168)
(164)
Actualisation cost on defined employee benefit debt
(29)
(45)
Interest income on pension plan assets
4
6
Financial transaction tax
(46)
(37)
Late interest due in connection with tax reassessments and employee-related litigation
(55)
(3)
Dividends received on available-for-sale financial assets
1
1
Proceeds from the sale of available-for-sale financial assets measured at fair value through equity
7
48
Cost of sold available-for-sale financial assets measured at fair value through equity
(2)
(40)
Exchange gains and losses
7
1
Cost of bond buybacks
(7)
(3)
Variation valuation Cash flow hedge
(3)
(31)
Other
(44)
(61)
FINANCE COSTS AND OTHER FINANCIAL INCOME AND EXPENSES, NET
(515)
(563)
Financial expenses
(567)
(654)
Financial income
51
91
Risk management
12.6
The main risks associated with the financial instruments used by the Corporate Treasury and Financing oversees the proper implementation
Group are liquidity, interest rate, currency, credit and equity risks. The of the rules governing the consumer credit business, jointly with the
Group's policy for managing these risks is described below.
other investors in the business where applicable. A reporting system
exists between local teams and Corporate Treasury and Financing.
Due to the differing natures of the various businesses, financial risks
arising from the bancassurance business (including Carrefour Banque
Liquidity risk
12.6.1
in particular) are managed separately from those related to the retail
business.
Retail business
12.6.1.1
An organization has been set up around a cash-pooling system to track
financial risks. The Corporate Treasury and Financing department
Liquidity risk is the risk that Carrefour will be unable to settle its
based in Brussels manages the treasury and financing needs of all
financial liabilities when they fall due.
retail subsidiaries, on the instructions of Group senior management. A The Group manages its liquidity risk by ensuring, to the extent
reporting system ensures that Group senior management can oversee possible, that it has sufficient liquid assets at all times to settle its
the department’s implementation of the approved management
liabilities when they fall due, whatever the conditions in the market.
strategies.
A Liquidity Committee meets at monthly intervals to check that the
The risks associated with the consumer credit business are managed Group’s financing needs are covered by its available resources.
and tracked directly by the entities concerned.
210
2015 REGISTRATION DOCUMENT