

 188 / 302

Consolidated Financial Statements as of December 31, 2015
Notes to the Consolidated Financial Statements
Income tax
Note 8
Accounting policies
Income tax expense comprises current taxes and deferred taxes. It
They are measured at the tax rates that are expected to apply to the
includes the
Cotisation sur la Valeur Ajoutée des Entreprises
(CVAE)
period when the asset will be realized or the liability will be settled,
local business tax in France assessed on the value-added generated by
based on tax rates and tax laws that have been enacted or
the business, which is reported under income tax expense because the substantively enacted by the end of the reporting period. Deferred tax
Group considers that it meets the definition of a tax on income assets and liabilities are not discounted and are classified in the
contained in IAS 12 –
Income Tax
.
statement of financial position under "Non-current assets" and
"Non-current liabilities".
Deferred taxes are calculated on all temporary differences between the
carrying amount of assets and liabilities in the consolidated statement
The recoverability of deferred tax assets is assessed separately for each
of financial position and their tax basis (except in the specific cases
tax entity, based on estimates of future taxable profits contained in the
referred to in IAS 12), and carried-forward tax losses.
business plan for the country concerned (prepared as described in
Note 6.3) and the amount of deferred tax liabilities at the period-end.
A valuation allowance is recorded to write down deferred tax assets
whose recovery is not considered probable.
Income tax expense for the period
8.1
2015
2014
(in millions of euros)
Current income tax expense (including provisions)
(544)
(610)
Deferred income taxes
(54)
(99)
TOTAL INCOME TAX EXPENSES
(597)
(709)
Tax proof
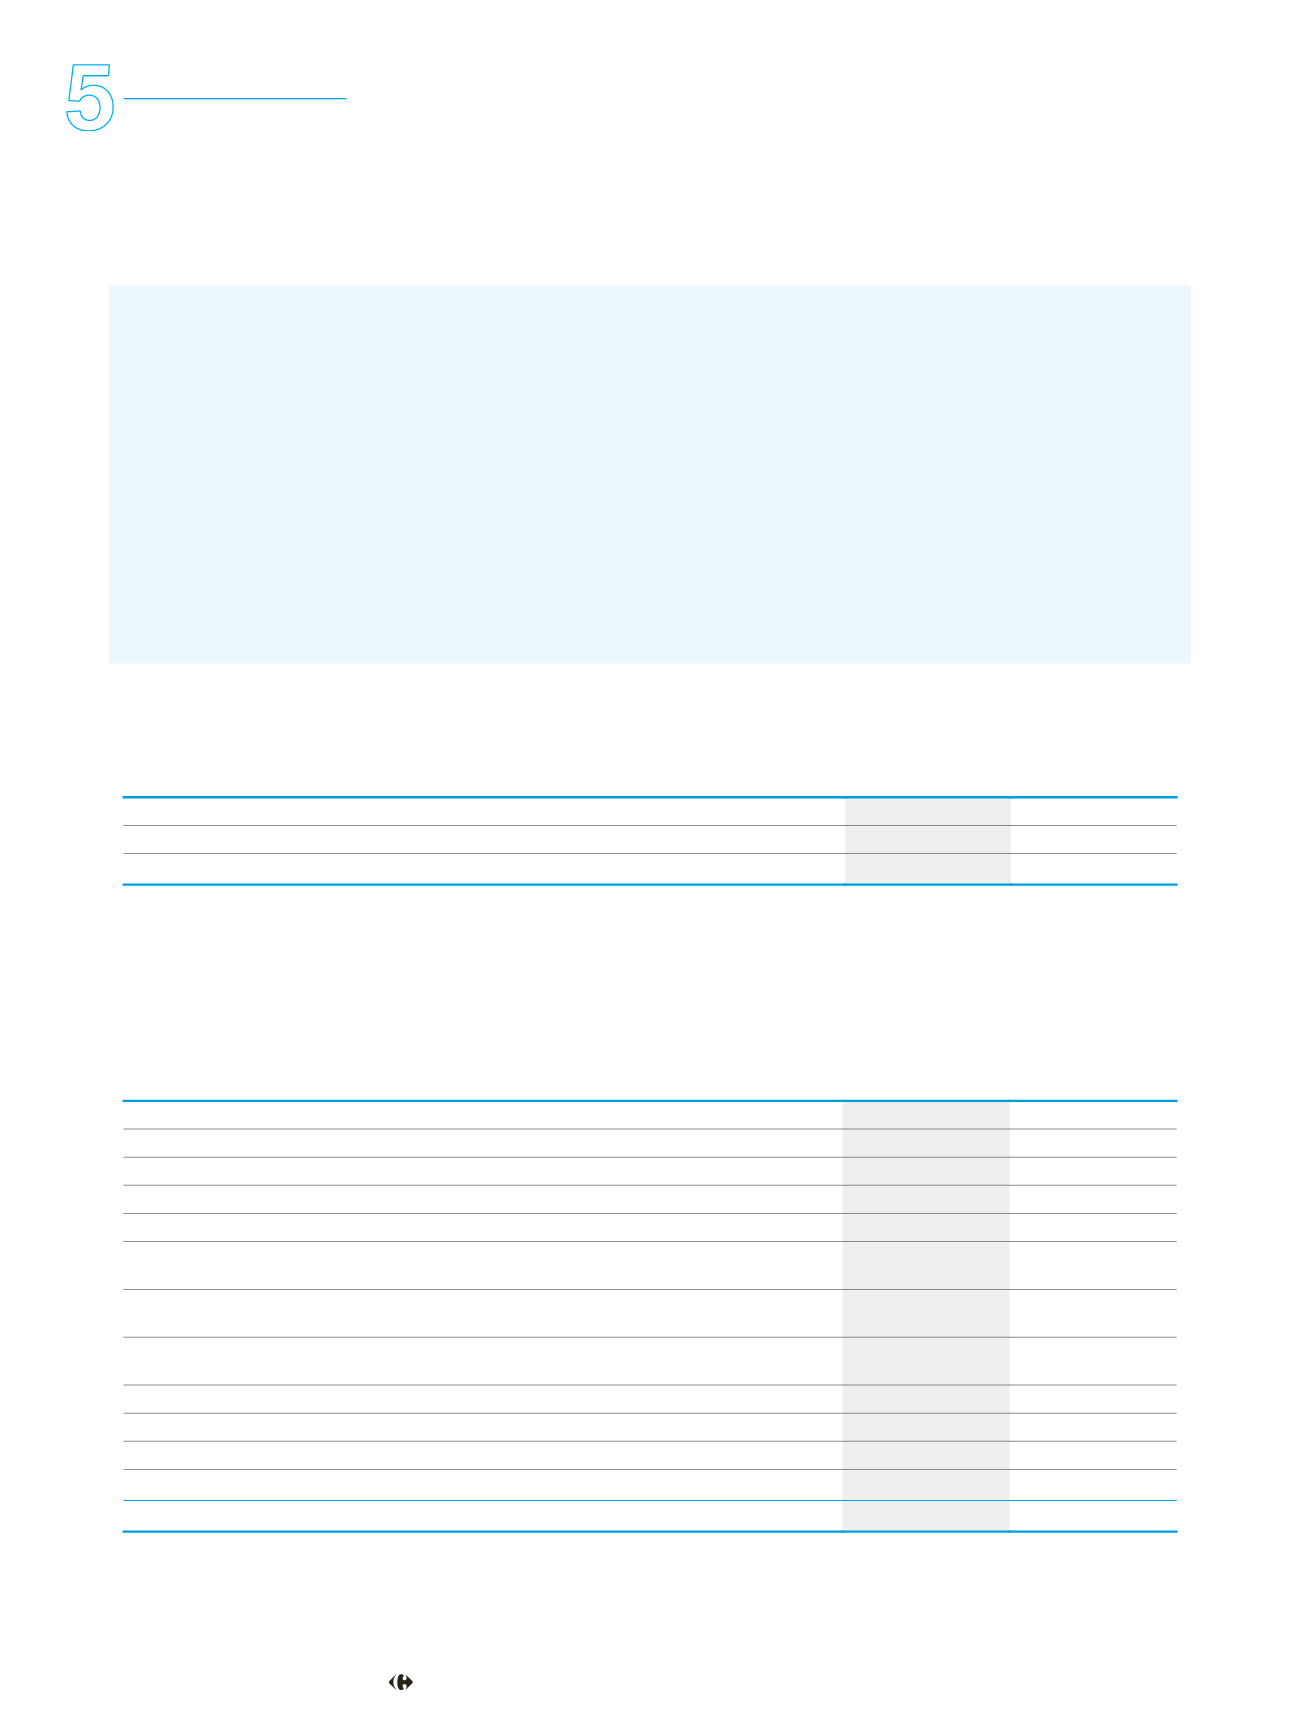
Theoretical income tax for 2015 and 2014 has been calculated by multiplying consolidated income before tax by the standard French corporate
income tax rate (including the 10.7%
contribution exceptionnelle
surtax applicable until December
30, 2016). For 2015, theoretical income tax
expense amounted to 652 million euros compared with actual net income tax expense of 597 million euros.
2015
2014
(in millions of euros)
Income before taxes
1,717
2,010
Standard French corporate income tax rate
38.0%
38.0%
Theoretical income tax expense
(652)
(764)
Differences in overseas nominal taxation rates
67
59
Adjustments to arrive at effective income tax rate:
Tax expense and tax credits not based on the taxable income (tax provisions, withholding
●
taxes, etc.)
(1)
(7)
32
Deferred tax assets not recognized on temporary differences and tax loss carryforwards
●
arising in the year
(61)
(147)
Deferred tax assets recognized on temporary differences and tax loss carryforwards of
●
previous years
(2)
105
55
Valuation allowances on deferred tax assets recognized in prior years
●
-
(20)
Tax effect of other permanent differences
●
(29)
24
Other differences
●
(19)
51
Total Income tax expense
(597)
(709)
Effective tax rate
34.8%
35.3%
The reported amount of taxes with no tax base notably takes into account changes in provisions for tax risks (Note 9.2.1). This caption also includes the CVAE
(1)
local business tax in France assessed on the basis of the value-added generated by the business, which is considered as meeting the definition of a tax on
income. This tax amounted to 64 million euros in 2015 (2014: 64 million euros).
Deferred tax assets recognized on prior years’ tax losses primarily concerned Brazil and Spain in 2015 and Italy in 2014.
(2)
188
2015 REGISTRATION DOCUMENT