

 172 / 302

Consolidated Financial Statements as of December 31, 2015
Notes to the Consolidated Financial Statements
Working capital
5.4
Change in working capital
5.4.1
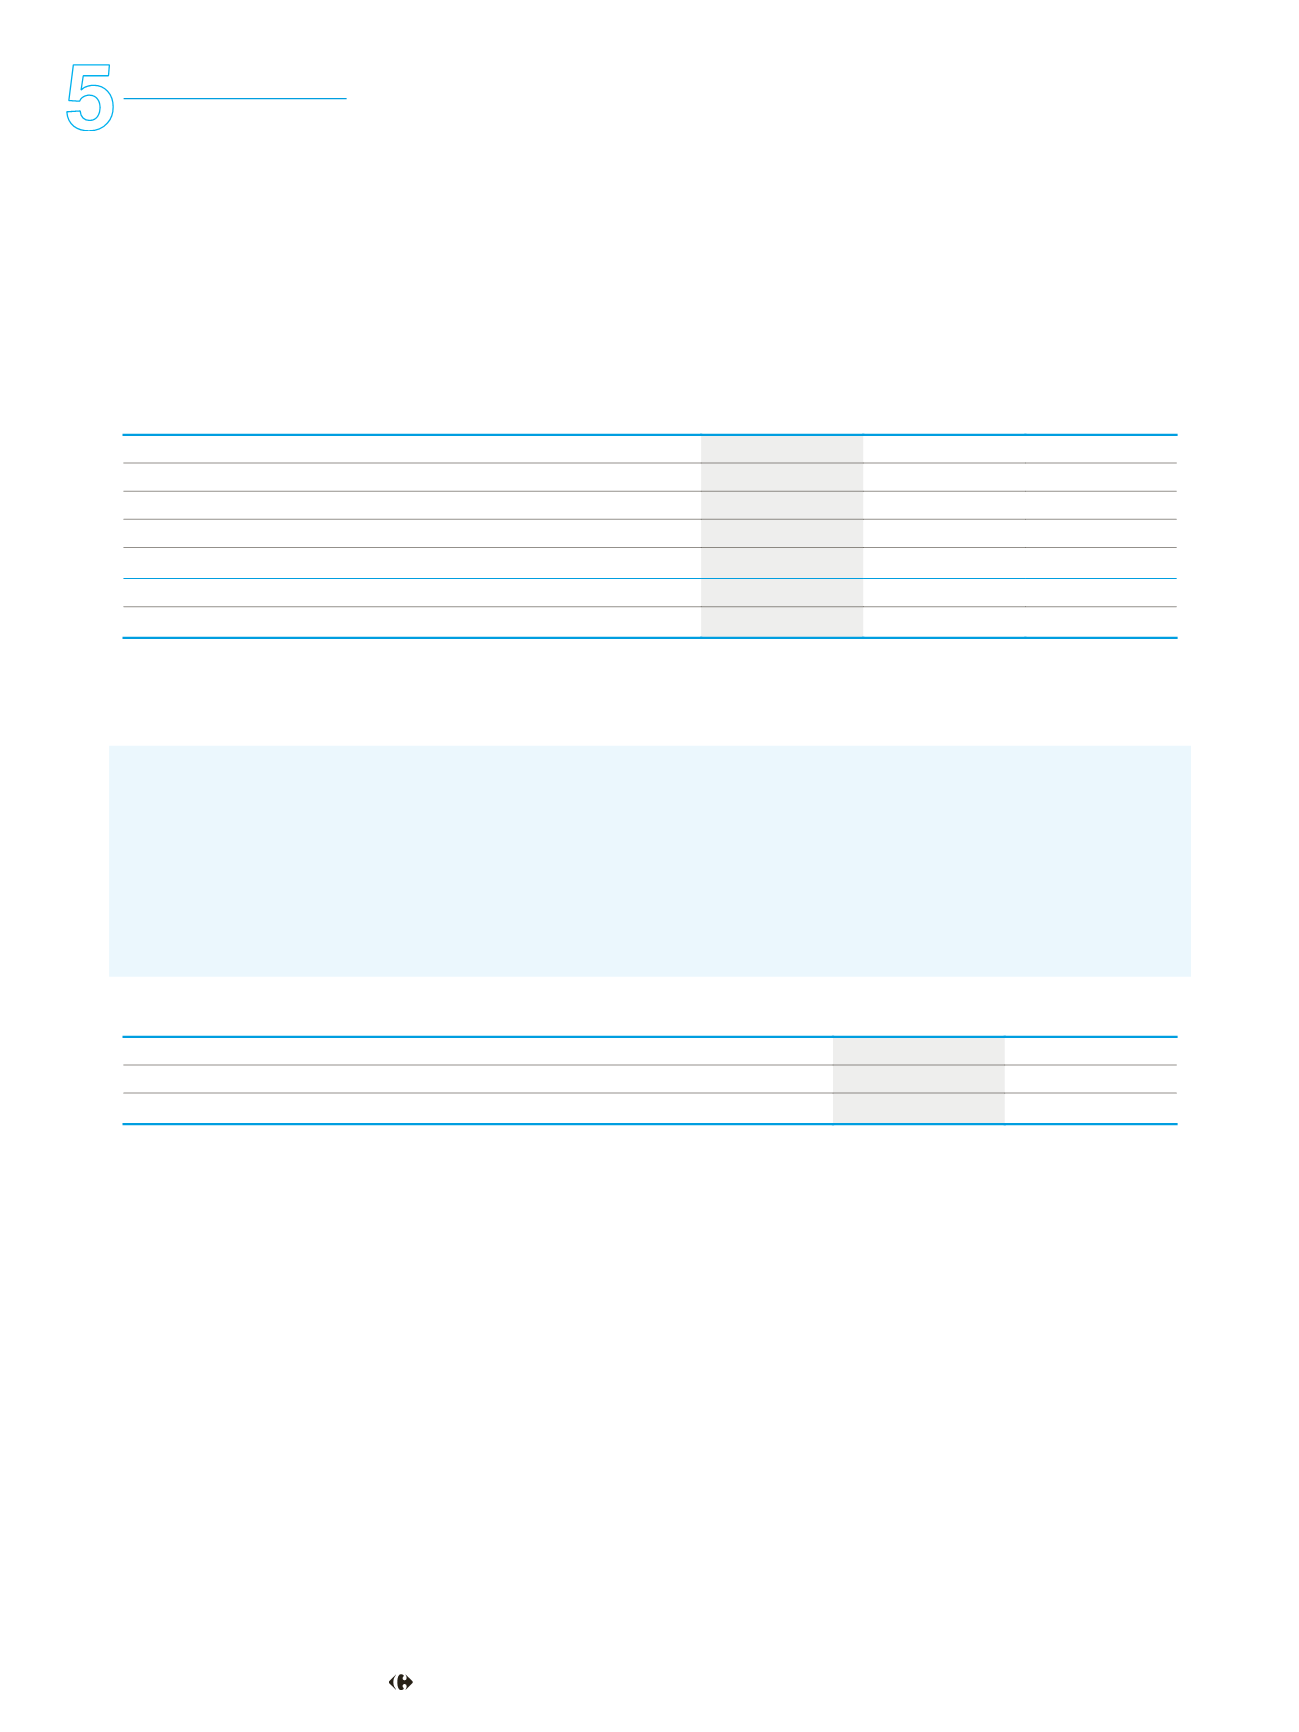
The change in working capital reported in the consolidated statement of cash flows under "Cash flows from operating activities" breaks down as
follows:
December 31, 2015
December 31, 2014
Change
(in millions of euros)
Change in inventories
(528)
(310)
(217)
Change in trade receivables
(69)
80
(149)
Change in trade payables
875
246
629
Change in loyalty program liabilities and other
(55)
(78)
23
Change in trade working capital requirement
224
(63)
287
Change in other receivables and payables
52
81
(29)
CHANGE IN WORKING CAPITAL REQUIREMENT
276
18
258
Working capital, like all other items in the statement of cash flows, is translated at the average rate for the period.
Inventories
5.4.2
Accounting policies
In accordance with IAS
2 –
Inventories
, goods inventories are The cost of inventories includes all components of the purchase cost of
measured at the lower of cost and net realizable value.
goods sold (with the exception of exchange gains and losses) and takes
into account the rebates and commercial income negotiated with
Cost corresponds to the latest purchase price plus all related expenses.
suppliers.
This method is appropriate given the rapid inventory turnover, and the
resulting values are close to those obtained by the first in-first out
Net realizable value corresponds to the estimated selling price in the
(FIFO) method.
ordinary course of business, less the estimated costs necessary to
make the sale.
December 31, 2015
December 31, 2014
(in millions of euros)
Inventories at cost
6,595
6,444
Impairment
(233)
(231)
INVENTORIES, NET
6,362
6,213
172
2015 REGISTRATION DOCUMENT