

 149 / 302

Management’s discussion and analysis as of December 31, 2015
Parent company financial review
Income appropriation
4.6.3
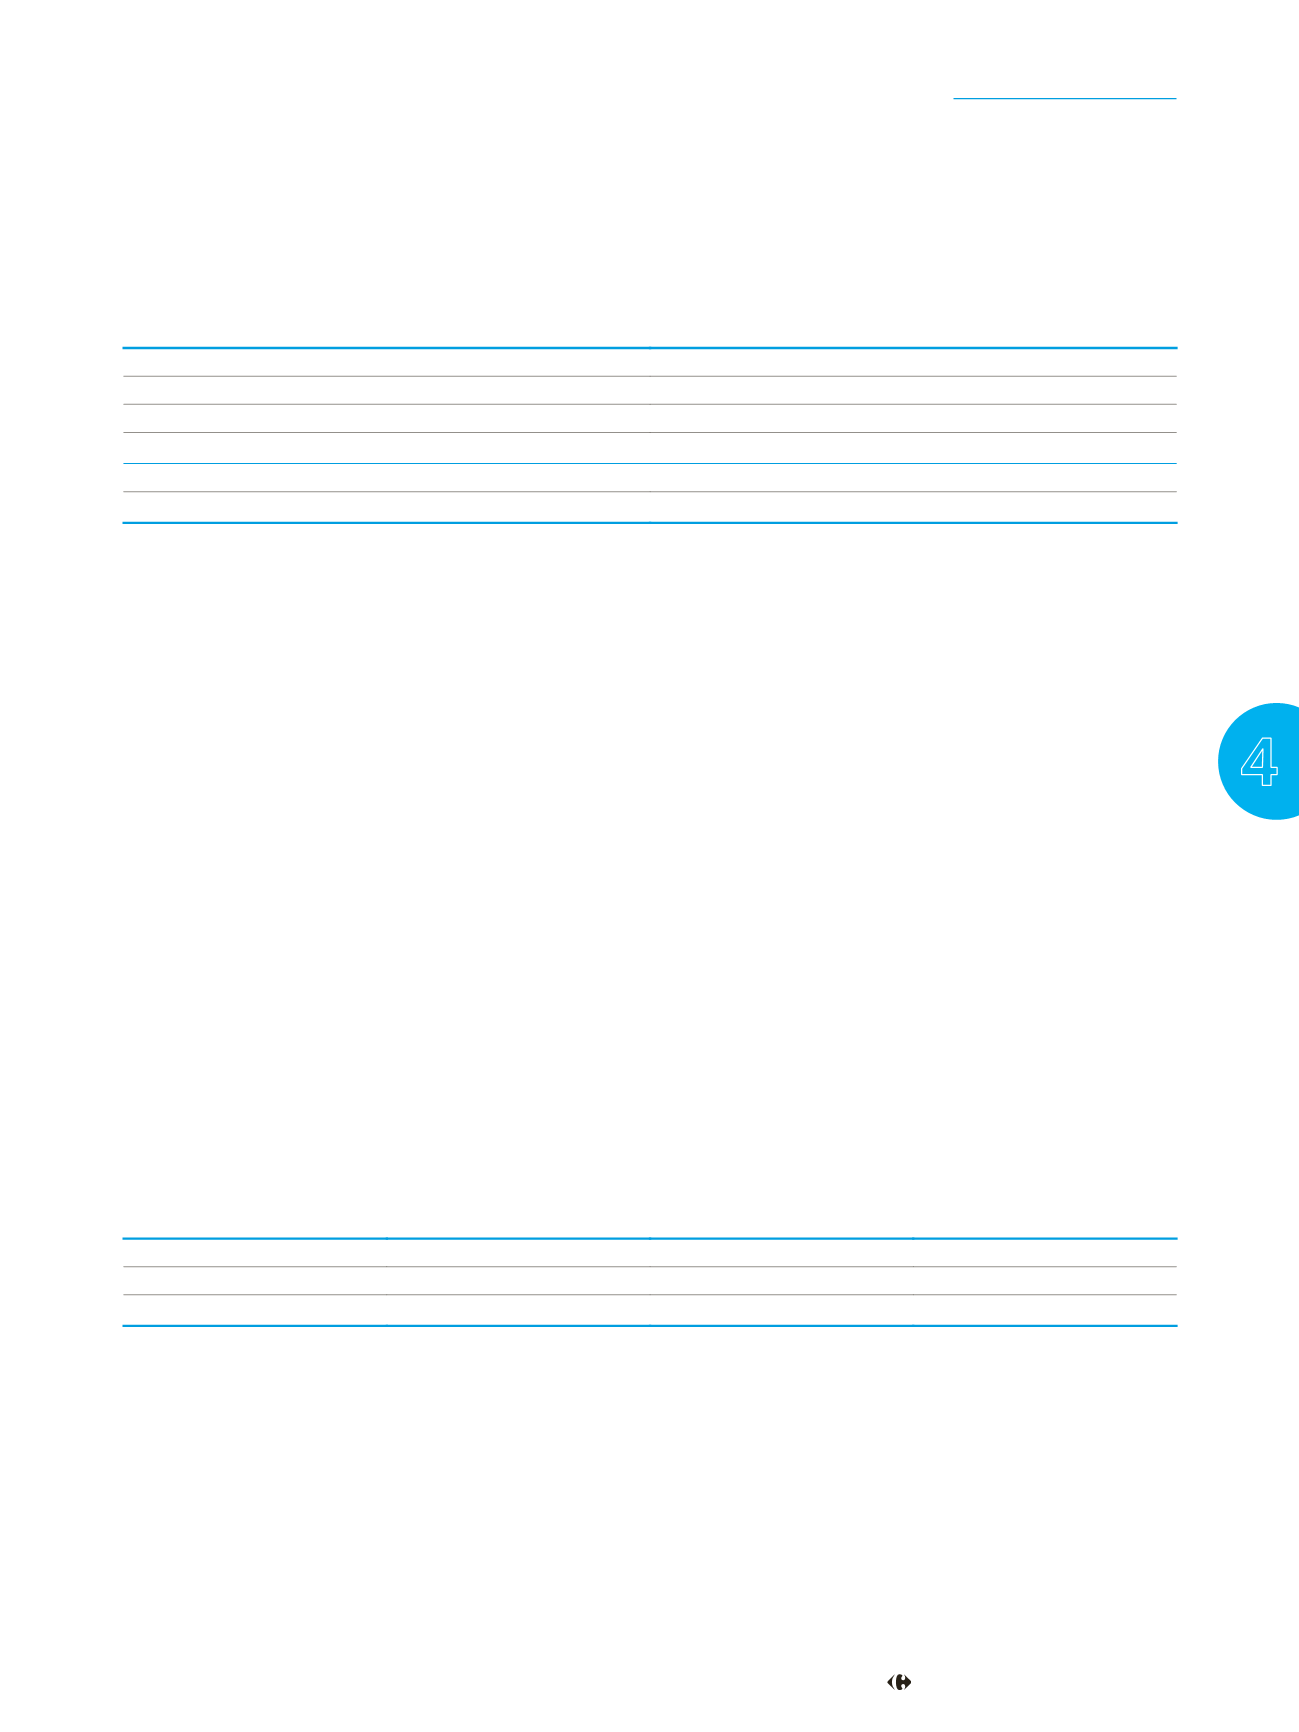
It is proposed to the Shareholders to allocate and distribute earnings for the fiscal year as follows:
Profit for fiscal year
€830,629,260.99
Allocation to the legal reserve
€(889,221.25)
Retained earnings at December 31, 2015
€5,213,006,730.57
Total distributable profit
€6,042,746,770.31
2015 Dividends paid out of distributable profit
€516,929,555.80
Balance of retained earnings after allocation
€5,525,817,214.51
The amount of retained earnings after tax for fiscal year 2014 was
The new shares, if the option is exercised, will be issued at a price equal
increased owing to 2014 dividends not paid out on treasury shares.
to 90% of the average opening prices listed during the twenty stock
market trading sessions on Euronext Paris prior to the date of the
In the case of a variation in the number of shares eligible for a dividend
Shareholders' Meeting, less the amount of the dividend that is the
with respect to 738,470,794
shares comprising the share capital as of
subject of this resolution and rounded up to the nearest euro cent.
December
31, 2015, the total amount of dividends would be adjusted
Such issued shares will immediately be entitled to dividends as of
as a consequence and the amount allocated to retained earnings
January
1, 2016 and will be part of the share capital of the Company
would be determined on the basis of the dividends actually paid.
alongside other shares.
It is specified that the total dividend of € 516,929,555.80
which
Shareholders may opt for payment of the dividend in cash or in new
represents a dividend of € 0.70
per share, before payroll taxes and non
Company shares from May
23, 2016 to June
10, 2016 inclusive, by
final withholding tax of 21% provided for in article
117
quater
of the
sending their request to the financial intermediaries that are
French general tax code, qualifies, for individuals who are French tax
authorized to pay the dividend or, for registered shareholders listed in
residents, for the tax relief equal to 40% of the amount of the dividend
the issuer-registered accounts held by the Company, to its authorized
in accordance with Section
2° of paragraph
3
of article
158 of the
representative Société Générale, CS 30812, 44308 Nantes Cedex 03.
French general tax code.
For shareholders who have not exercised their option by June
10,
It is proposed to offer to the Shareholders the option of a dividend
2016, the dividend will only be paid in cash.
payment:
For shareholders who have not opted for a payment in shares, the
in cash; or
●
dividend will be paid in cash on June
21, 2016 after the expiration of
in new Company shares.
●
the option period. For shareholders who have opted for a dividend
payment in shares, the settlement and delivery of shares will take place
on the same date.
It is recalled to the Shareholders in accordance with the law, that the dividends paid on each share for the three preceding fiscal years and the
income eligible for tax relief under Section 2° of paragraph 3
of article 158 of the French general tax code per share, were as follows:
Dividends eligible
Dividends non eligible
Fiscal year
Gross dividend paid
for tax relief of 40%
for tax relief of 40%
2012
€0.58
€0.58
-
2013
€0.62
€0.62
-
2014
€0.68
€0.68
-
2015 REGISTRATION DOCUMENT
149